Financial Risk Management & Asset Protection for Entrepreneurs
The Vulnerability of Growth
As an entrepreneur, building a successful business takes years of disciplined labor, late nights, and calculated risks. Yet, without proper asset protection and risk management, a single catastrophic event (like a frivolous lawsuit, an unexpected disability, an economic shock, or a partner dispute) can wipe out decades of accumulated wealth in a matter of months.
Proverbs 27:12 offers sound advice for leaders:
“The prudent see danger and take refuge, but the simple keep going and pay the penalty.”
Taking proactive steps to shield your family and business from downside risk is not a sign of fear or lack of faith; it is an act of biblical prudence. Protecting what God has helped you build ensures that your family, employees, and operations remain secure during severe trials.
Separating Personal and Business Liabilities
One of the most common mistakes made by growing business owners is failing to properly isolate liability between their business operations and their personal family assets.
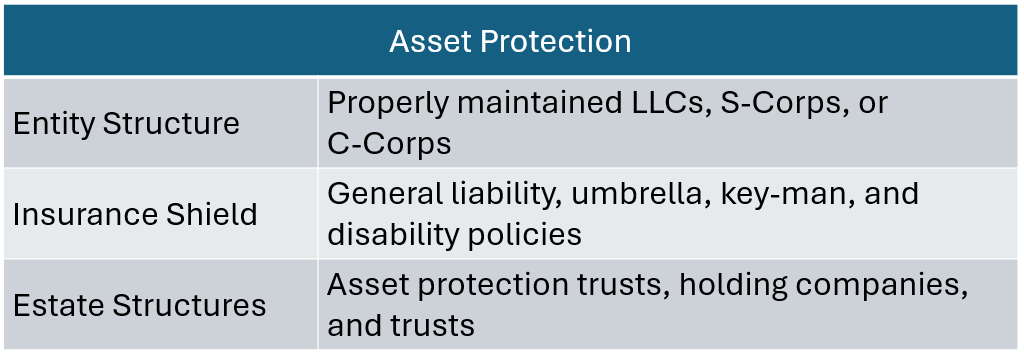
- Maintain Strict Corporate Formalities: Operate your business under an appropriate legal structure (e.g., LLC, S-Corp, or C-Corp). Never commingle personal funds with business accounts, as doing so can allow creditors to “pierce the corporate veil” and pursue your personal home, bank accounts, or investments.
- Use Holding Companies for High-Value Assets: Consider holding real estate, equipment, or valuable intellectual property in separate LLC entities that lease assets back to your primary operating company.
Comprehensive Insurance Coverage: Your First Line of Defense
Insurance is simply transferring catastrophic financial risk to a third party for a predictable monthly fee. Ensure your coverage includes:
- Commercial General Liability & Cyber Risk: Protects against customer injuries, property damage, and data breaches.
- Personal & Commercial Umbrella Policies: Provides extended liability coverage beyond standard auto or home limits (e.g., $2M to $5M policies).
- Key-Man Insurance: A life insurance policy owned by the business on critical leaders (such as yourself) that provides cash flow to stabilize operations should an executive pass away unexpectedly.
- Disability Insurance: Protects your household income if an injury or illness prevents you from working in your business for an extended period.
Diversifying Away from Business Concentration Risk
For many founders, 90% or more of their net worth is tied up in their operating company. While this concentration is natural during early growth phases, it creates extreme risk over time.
As your company generates profits, systematically harvest capital out of the business and reallocate it into diversified, non-correlated assets—such as cash reserves, real estate, high-quality index funds, or precious metals. This ensures your family’s financial security remains intact even if your primary industry experiences severe disruption.
Prudent Defense for Sustained Offense
Great business leaders understand that long-term success requires playing both offense and defense. By establishing robust entity structures, carrying proper insurance, and diversifying your family’s assets, you shield your stewardship assignment from unexpected storms and secure your family’s financial future.